Refinance My Mortgage Home Loan Repayment Calculator
Calculate home loan repayments with our Home Loan Repayment Calculator. View detailed amortization charts, compare loan terms, and plan your mortgage with confidence.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual costs and repayments may differ.
Home Loan Details:
Important!
Home Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Home Loan Amortisation Calculator
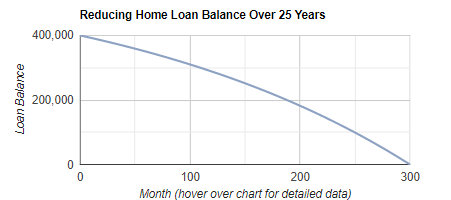
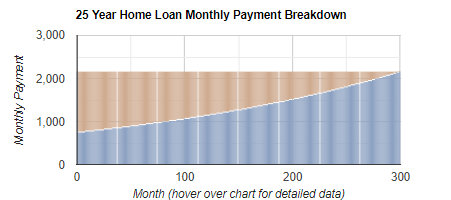
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Home Loan Repayment Calculator
Our Home Loan Repayment Calculator helps you estimate your mortgage repayments in Australia and understand how a loan may reduce over time. It is useful for budgeting, comparing loan terms, and visualising an amortisation schedule (how each repayment is split between interest and principal). The calculator is designed for planning only and works best when you enter realistic assumptions.
Important information: Results are estimates only and do not constitute a quote. Interest rates and loan features vary by lender and may change. This information is general and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you and seek professional advice if required.
How to complete the calculator fields (in order):
1. Purchase Price: Enter the property purchase price. If you expect to borrow extra for costs, you may choose to include amounts such as stamp duty, insurance, and other buying costs in this figure so your estimate reflects your likely loan size. Enter whole numbers only (no dots or commas).
2. Deposit or Equity Value: Enter your cash deposit or usable equity from another property (if applicable). A higher deposit generally reduces the loan amount and can lower repayments. Enter whole numbers only (no dots or commas).
3. Term of Loan (years): Select the number of years to repay the loan. Longer terms usually reduce repayments but increase total interest paid over the life of the loan.
4. Interest Rate (% per annum): Select an interest rate for the simulation. Use a realistic rate and consider testing higher rates to understand “rate rise” risk.
5. Calculate: Click calculate to generate your results.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability checks, remembering real loans may include fees and different features.
2. Amortisation charts: Review the loan balance chart to see how your balance falls over time, and the interest versus principal chart to understand how early repayments are typically interest-heavy, then shift toward principal reduction later.
3. Compare scenarios: Adjust the term, deposit/equity, or interest rate and recalculate to compare loan terms and see how changes affect repayments and total interest over time.
Fresh housing finance reporting continues to show investor lending as one of the more resilient areas of the Australian mortgage market. For homeowners thinking about refinancing, that matters because lenders do not assess every borrower in the same way. Loan purpose, income stability, equity position and repayment buffer can all influence both approval prospects and the sharpness of the rate offered. - read more
Fresh lending indicators suggest Australian borrowers are still engaging with the mortgage market, even as higher repayments continue to shape household decisions. New housing finance activity has shown signs of resilience, with owner-occupiers, investors and refinancers all weighing up whether current loan settings still make sense in a market where lender pricing remains uneven. - read more
Fresh home loan rate reporting suggests competition for quality borrowers remains active, even while many existing mortgage holders continue to feel the weight of elevated repayments. The key issue is not simply whether rates are high or low. It is whether lenders are reserving their sharpest pricing for new customers, refinancers and borrowers with strong equity positions, rather than automatically passing similar value to long-term customers. - read more
Fresh property market reporting points to a more confident housing backdrop heading into spring, with buyer activity and listing conditions showing signs of improvement across parts of Australia. For homeowners considering a refinance, this is more than a real estate headline. After a period of earlier softness, firmer values can change the conversation with lenders. - read more
Mortgage refinancing involves replacing your existing home loan with a new one, usually to take advantage of better interest rates or terms. By switching lenders or renegotiating with your current lender, refinancing can lead to lower monthly payments, reduced loan terms, or access to equity for other expenses. - read more
Refinancing can reduce repayments or improve loan features, but fees can affect whether switching is worthwhile. Learn the common refinancing costs in Australia and how to estimate your break-even point. - read more
In the realm of homeownership, mortgage refinancing stands out as a valuable tool for financial management. At its core, refinancing refers to the process of revising and replacing the terms of your existing mortgage agreement. Homeowners choose this path for various reasons, such as accessing a better interest rate, altering the loan term, or tapping into home equity. - read more
Mortgage refinancing refers to the process of replacing your existing home loan with a new one, typically under different terms. Essentially, you're paying off your old mortgage with a new loan. This can be an extremely useful financial maneuver, allowing homeowners to benefit from better interest rates or change their loan type to suit their current needs. - read more
Knowledgebase
Hard Inquiry: A credit report check by a lender or other entity as part of the credit approval process, which can lower your credit score.